On this page
A blockchain is a shared digital ledger: a database that stores records in linked blocks and is copied across many computers instead of being held by one central party. Each new block is cryptographically tied to the one before it, which makes recorded data very hard to alter without detection.
Key takeaways
- A blockchain is a database that stores transactions in blocks chained together and shared across a peer-to-peer network.
- Digital signatures and cryptography protect each transaction, and no single authority controls the ledger.
- Uses reach beyond cryptocurrency, including finance, medical records, intellectual property and food supply tracking.
- Drawbacks include weak regulation, which criminals have exploited, and high technology and energy costs.
- Blockchain is not the same as cloud computing: one is a tamper-resistant ledger, the other is a service delivery model.
What is a blockchain?
A database is an organized collection of data stored electronically. Data in a database is usually arranged in tables, so it can be searched and filtered efficiently. Large databases run on powerful servers, and many users can read the same data at the same time.
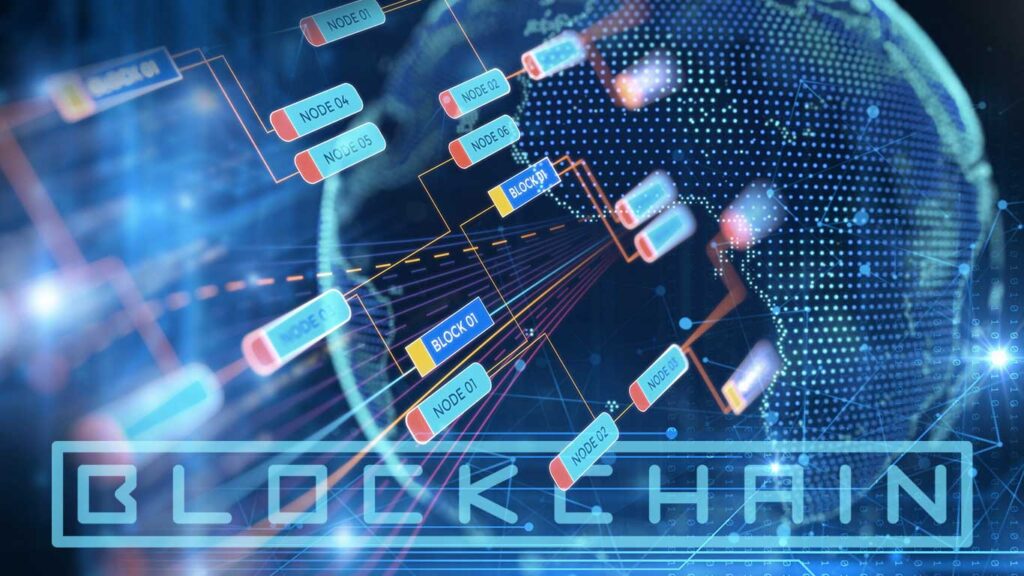
A blockchain is a special kind of database. It stores transaction records in units called blocks, and the blocks are linked into a chain. Copies of the chain are held by many computers, called nodes, that are connected peer to peer. For this reason a blockchain is often described as a digital ledger.
How does a blockchain work?
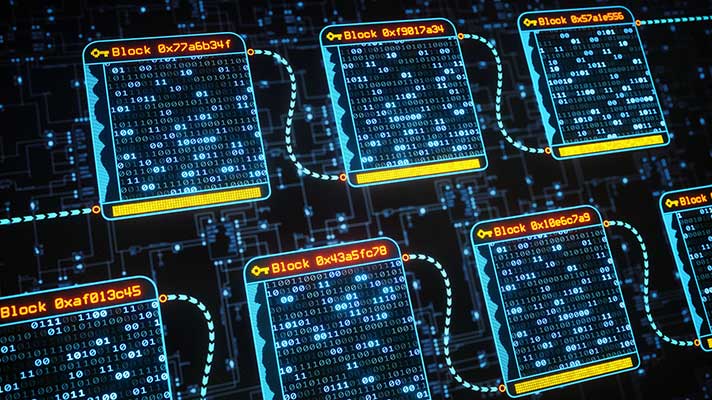
The process starts when a user makes a transaction on a blockchain platform. The transaction is packaged into a block and broadcast to the peer-to-peer network of nodes, which validate it.
Once the network confirms the transaction, the new block is added to the existing chain. Every transaction carries the owner’s digital signature, which proves it is genuine and guards against tampering.
Each new block is bound to the previous one using cryptography. Changing an old record would break the links that follow it, which is why data on a blockchain is considered highly secure.
Where is blockchain used?

Cryptocurrency is the best-known use, but the technology applies more widely. In finance it can help track fraudulent transactions. It can also be used to transfer intellectual property between businesses or artists, and to share a patient’s medical records securely.

A well-known business example is IBM Food Trust, a blockchain for the food supply chain. When salmonella or E. coli outbreaks occur, finding the source and reach of contamination has traditionally taken weeks. A shared ledger that follows a product from producer through supplier and retailer to delivery can trace a contaminated item back to its origin and show where else it may have been exposed.
Companies reported as of 2021 to have adopted blockchain technology include Walmart, Pfizer, Unilever, AIG and Siemens.
What are the benefits of blockchain?
Security and availability
Digital signatures and cryptographic algorithms make it difficult to alter data without the owner’s approval, and no outside party is needed to guarantee integrity. Records are effectively immutable once confirmed.
A blockchain also runs on a peer-to-peer network rather than a single central system. If one participant goes offline, the others keep working, so the network stays available.
Decentralization
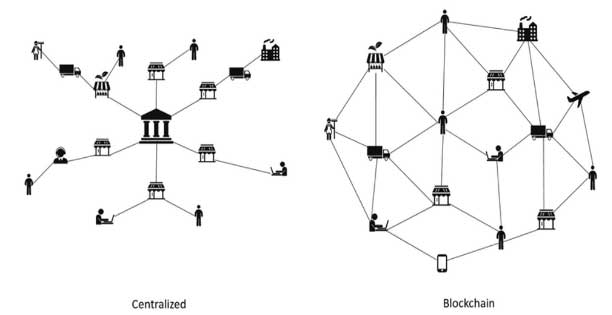
In a traditional arrangement, a transaction often needs approval from an administrative or regulatory authority. On a blockchain, participants reach agreement through consensus, so no third party has to approve each exchange.
The data is not kept in one central database. It is duplicated and spread across the network, which makes manipulation hard. If one copy falls into the wrong hands, only that copy is exposed rather than the whole network.
Transparency and efficiency
Because there is no centrally controlled authority, participants can see the shared record, which supports transparency. Banks and similar institutions work within business hours and time zones, while a blockchain network runs around the clock, every day of the year. Transactions can settle in minutes and may avoid some administrative fees.
What are the limitations of blockchain?
Lack of regulation
Privacy and strong security also mean that no regulator polices activity on the network. Silk Road is the standard example: an online black market on the dark web that ran from 2011 until the FBI shut it down in 2013. Illegal purchases there were paid for in cryptocurrency.
Cost of the technology
Blockchain can reduce administrative fees, but the technology itself is expensive to run. In Bitcoin mining, the electricity cost must be lower than the reward a miner earns to make a profit. A miner who adds a block to the Bitcoin blockchain is paid in bitcoin, which is meant to cover those costs.
How is blockchain different from cloud computing?
The two are often confused, but they solve different problems.
| Point of comparison | Blockchain | Cloud computing |
|---|---|---|
| Main purpose | Tamper-resistant ledger database | On-demand computing services, notably storage |
| Security basis | Cryptography, with no reliance on a third-party authority | Depends on the provider and how the service is configured |
| Nature | A technology, not a service | A delivery model offering SaaS, PaaS and IaaS |
| Records | Immutable | Mutable |
| Examples | Bitcoin, Ethereum, Quorum | AWS, IBM, Google, Microsoft |
Frequently asked questions
Is blockchain the same as Bitcoin?
No. Bitcoin is a cryptocurrency that runs on a blockchain. Blockchain is the underlying ledger technology, which can be used for many other purposes.
Why is blockchain considered secure?
Each transaction is signed by its owner, and each block is cryptographically linked to the previous one. Because copies are spread across many nodes, altering one copy does not change the network’s shared record.
Can blockchain data be changed?
Confirmed records are designed to be immutable. Changing one would break the links to every later block and would be rejected by the rest of the network.
What is the main drawback of blockchain?
The technology can be costly to run, and a lack of central oversight lets illegal activity such as the Silk Road marketplace take place without easy tracing.
Conclusion
Blockchain is a distributed, cryptographically secured ledger that removes the need for a central authority to keep records trustworthy. Its uses extend well beyond cryptocurrency, though cost and regulation remain real concerns. As adoption grows, it is likely to influence how many industries store and exchange data.