Tokenized shares ought to give crypto-native investors access to equity exposure through crypto platforms, however a token that tracks a share price is not automatically a share. The diversification case rests on whether holders gets real legal rights, whether assets sit within regulated custody arrangements, and whether or markets maintain reliable liquidity.
The market backdrop has shifted. The 5-year US Treasury yield moved above 5% in September for the first time since 2007, and the Federal Reserve raised its focus range by 25 basis points on September 16. Higher yields provide investors a more aggressive option to risk assets, improving comparisons between equities, crypto, and government debt.
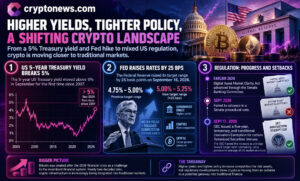
At the same time, the industry is shifting beyond crypto’s original outsider posture. Bitcoin appeared after the 2008 financial crisis as a challenge to parts of the incumbent financial system; around 2 decades later, crypto infrastructure is gradually being considered as a route into traditional markets.
The Digital Asset Market Clarity Act advanced by the Senate Banking Committee earlier in 2026 but failed to advance in a September procedural vote. One day later, on September 17, the SEC issued a 5-year, temporary, and conditional Innovation Exemption for certain Tokenized Securities Venues. The agency framed the measure as a bridge toward to longer-term rulemaking, not a permanent redesign of US market structure.
The shift has portfolio implications. Crypto benchmarks can stay closely targeted in bitcoin and ether, leaving many digital-asset portfolios exposed to overlapping crypto-market drivers even when they preserve numerous tokens.
Diversification Relies on What Each Tokenized Stocks Represent
For investors targeted in Bitcoin, Ethereum, stablecoins, and DeFi assets, tokenized US equities ought to add exposure to companies and sectors beyond crypto. Crypto platforms could also become distribution and trading infrastructure for assets that originated in traditional finance, bringing stock exposure into a familiar digital-asset environment.
Tokenized stocks may still respond to wide risk-off move, and get access to another asset class does not assure that a portfolio is balanced. The beneficial measures is the exposure the product in actually delivers, together with its legal claim and its market behavior, not the fact that it trades on-chain.
The SEC exemption makes the ownership question explicit: tokenized shares traded under the framework ought to offer holders the same rights as the equivalent traditional shares. A venue must also provide an issuer note and an possibility to object before listing a tokenized share created by an unaffiliated third party.
There is also a potential efficiency argument. Blockchain-based settlement and programmable infrastructure might also reduce some friction in issuing, moving, and trading financial assets, however those benefits stay a possibility instead of than a tested final results of this exemption. Tokenization does not remove the underlying investment’s market risk or the require for disclosure, governance, and market safeguards.
The SEC Pilot Tests Access
The Innovation Exemption offers qualifying Tokenized Securities Venues temporary relief from being treated with as exchanges under the usual definition when they facilitate restricted trading of genuine National Market System stocks by permissioned automated market makers and liquidity pools.
Certain liquidity providers also acquire temporary, conditional relief from dealer-registration necessities. The structure creates a bounded environment for market participants and regulators to observe how tokenized equities perform. It does not settle the rules for every crypto platform, nor does it establish that on-chain trading will provide deep markets.
Custody provides a parallel test. Tokenized equities can also connect on-chain trading to regulated financial infrastructure, however investors still want to understand how assets are held and how the custody model operates during disruption or insolvency. Custody and execution controls stay vital considerations in that infrastructure.
Tokenized stocks may make portfolio diversification more reachable to crypto-native investors, but the investment case is only as robust as the rights attached to the token, the custody behind it, and the liquidity available when a position required to be unwound.
The SEC experiment is best read as a test of coexistence between crypto and Wall Street, not as evidence that one system has displaced the other.